By CA Arpan Bohra (FCA, CS), Arpan Bohra & Co., Chartered Accountants, Hyderabad. Position of law as at 21 November 2026.
Two kinds of early money, and two very different relationships.
A founder in Hyderabad is building a logistics software product. A retired industrialist offers ₹40 lakh for a small stake. A week later, a fund partner asks for a meeting. The question every founder faces is angel investor vs venture capitalist: who should take the first cheque, and what comes with it?
Both put money into a young company in exchange for shares, and both hope the shares become far more valuable. They differ in whose money it is, how much they write, how they are regulated and what they expect to see before and after the cheque. This article explains each point in plain words.
An angel investor invests their own money, usually at an early stage and in smaller amounts, either directly or through a SEBI-registered angel fund. A venture capitalist manages pooled money from fund investors, usually through a SEBI-registered Category I Alternative Investment Fund, and typically writes larger cheques with a structured exit in mind. Neither is better in the abstract. The right choice depends on your stage, the amount you need and the kind of help you want.
Who they are, in plain English
An angel investor is usually a wealthy individual, often a former founder or senior executive, who invests personal money in a very young business. A venture capitalist (VC) is a professional fund manager who invests money collected from other people, such as family offices, institutions and wealthy individuals, in startups that could grow very quickly.
An angel writes a personal cheque. A VC writes a cheque from a pool it has promised to return, with profit, to its own investors. That one difference explains most of the others: a VC answers to fund investors, so it usually asks for stronger rights and a bigger exit.
What the law says about each
The legal position differs for each type of investor. The table sets out the main points as they stand today.
| Investor | Legal position | Points to know |
|---|---|---|
| Individual angel | Subscribes to shares issued by the startup. No separate SEBI registration is needed for an individual investing their own money. | The startup carries the company-law steps: approvals, valuation, allotment and filings. A foreign individual invests under the FDI policy and the FEMA rules, with reporting. |
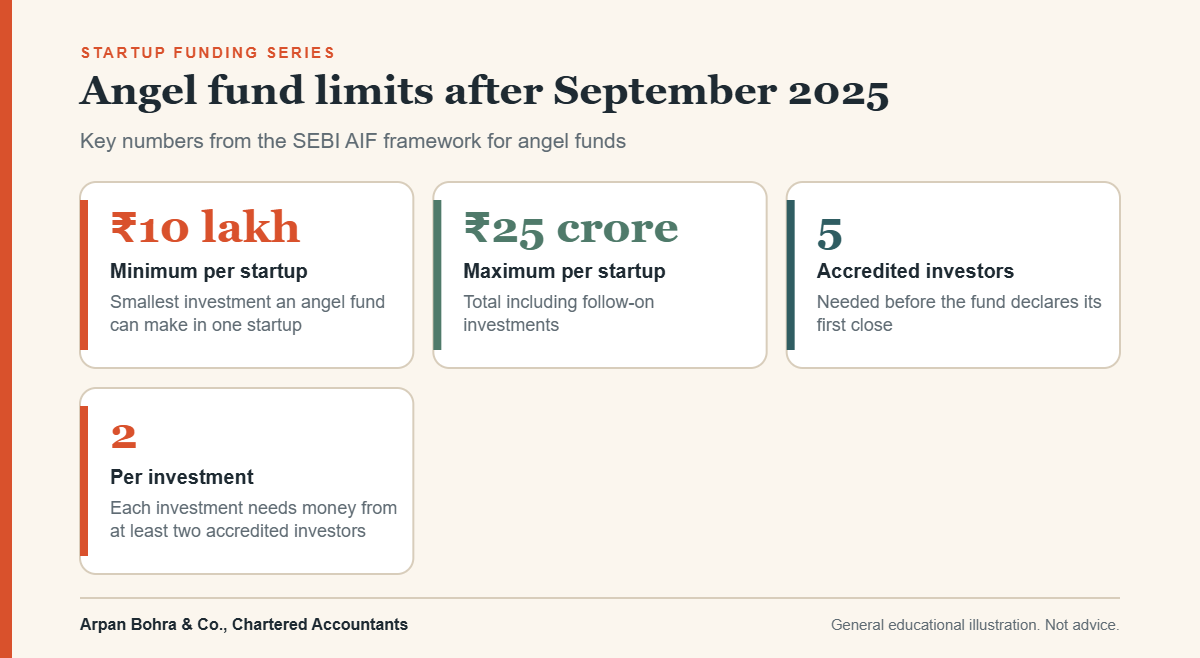
| Angel fund | A Category I Alternative Investment Fund registered with SEBI under the AIF Regulations, 2012. | Since the September 2025 amendment, an angel fund raises money only from accredited investors. Each investment in a startup must be between ₹10 lakh and ₹25 crore, including follow-on investment. |
| Venture capital fund | A Category I AIF (venture capital fund) registered with SEBI. | A typical AIF scheme requires each investor to commit at least ₹1 crore. The manager must follow SEBI rules on investing, reporting and governance. |
What happened to angel tax?
Section 56(2)(viib) of the Income-tax Act, 1961 (the so-called angel tax) taxed the premium a closely held company received above fair market value. It was made inapplicable from assessment year 2025-26, and the Income-tax Act, 2025 does not carry a corresponding provision. Valuation still matters, because the Companies Act, the FEMA pricing rules and your own accounting records need a defensible price, and earlier years can still be examined.
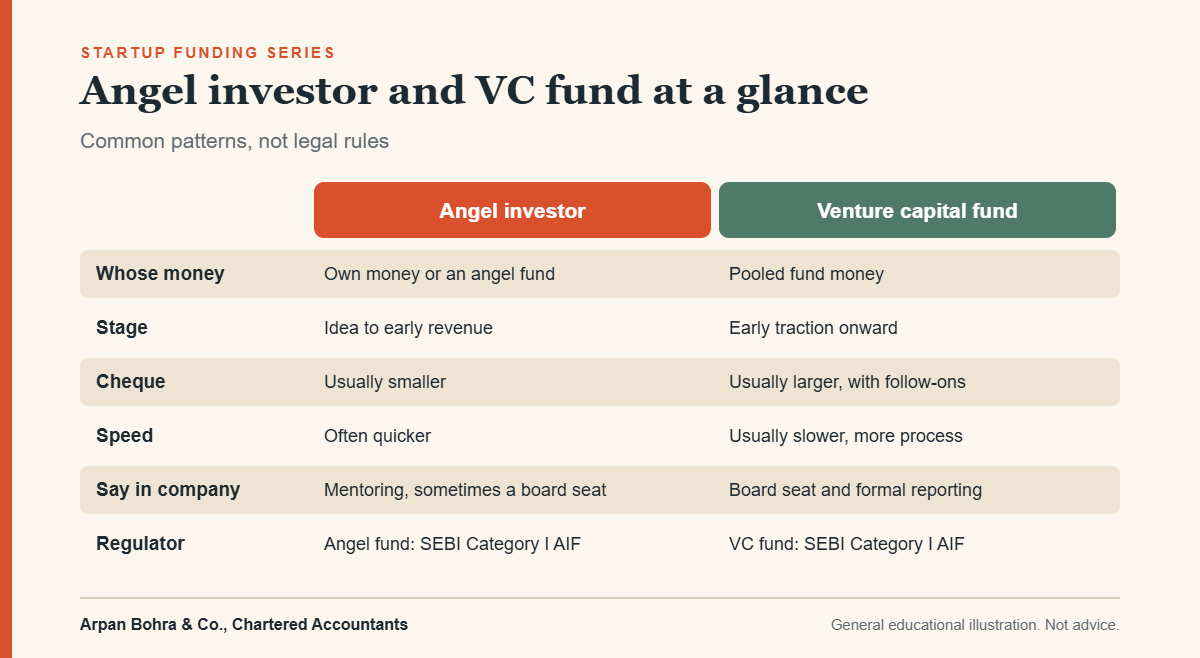
Angel investor vs venture capitalist: side by side
The patterns below are common in practice, not legal rules. Individual investors and funds vary widely.
| Point | Angel investor | Venture capital fund |
|---|---|---|
| Whose money | Own money, or an angel fund of accredited investors | Pooled money from the fund’s investors |
| Usual stage | Idea, prototype or early revenue | Early traction onward, including later growth rounds |
| Cheque size | Usually smaller, within the angel fund limits if invested through a fund | Usually larger and may include follow-on rounds |
| Decision speed | Often quicker, as one person or a small committee decides | Usually slower, with investment committee and legal review |
| Involvement | Mentoring and introductions are common | Board seat, reporting and active governance are common |
| Time horizon | Varies with the individual | Tied to the life of the fund and its return targets |
| Documents | Shorter, but a written agreement is still essential | Detailed subscription and shareholders agreements |
What each investor will ask for
These are negotiated contract terms, not legal requirements. Knowing them in advance prevents surprises when the term sheet arrives.
- Valuation and stake. Stake = investment ÷ post-money valuation. An investment of ₹1 crore at a post-money valuation of ₹5 crore gives the investor 20%.
- Liquidation preference. Decides who is paid first if the company is sold.
- Board seat or observer seat. A say in major decisions.
- Pro-rata right. The right to invest in later rounds to avoid dilution.
- Anti-dilution protection. Protects the investor if a later round is priced lower.
- Information rights. Regular accounts and reports.
An investor puts in ₹2 crore for 20% with a 1x non-participating liquidation preference. That means the investor takes the higher of its money back or its percentage share of the sale price.
- Company sold for ₹5 crore: 20% is ₹1 crore, which is less than ₹2 crore. The investor takes ₹2 crore and the others share ₹3 crore.
- Company sold for ₹20 crore: 20% is ₹4 crore, which is more than ₹2 crore. The investor takes ₹4 crore.
How to think about the choice
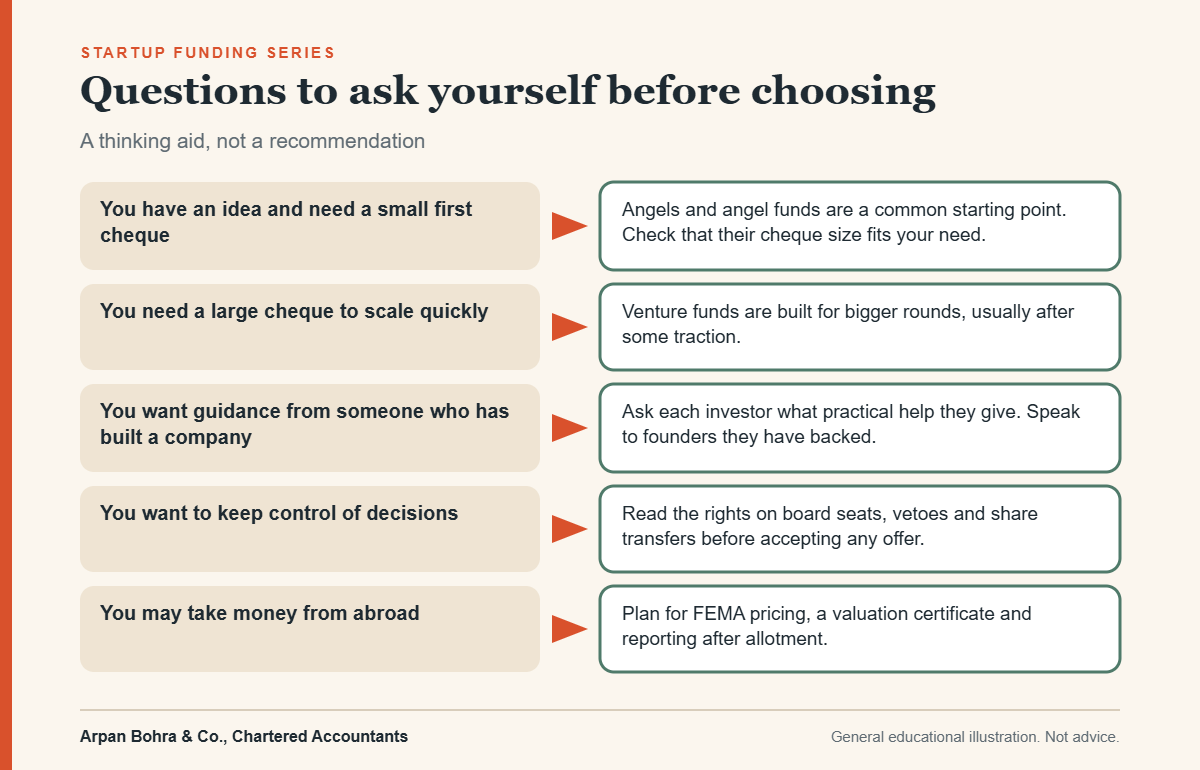
The table below is a thinking aid, not a recommendation. Each row pairs a common situation with a question to ask.
Founders in Hyderabad usually meet angels through founder networks, incubators and angel groups, and funds through introductions from other founders. In either case, speak to founders the investor has backed before and ask what happened when things did not go to plan.
From term sheet to money in the bank
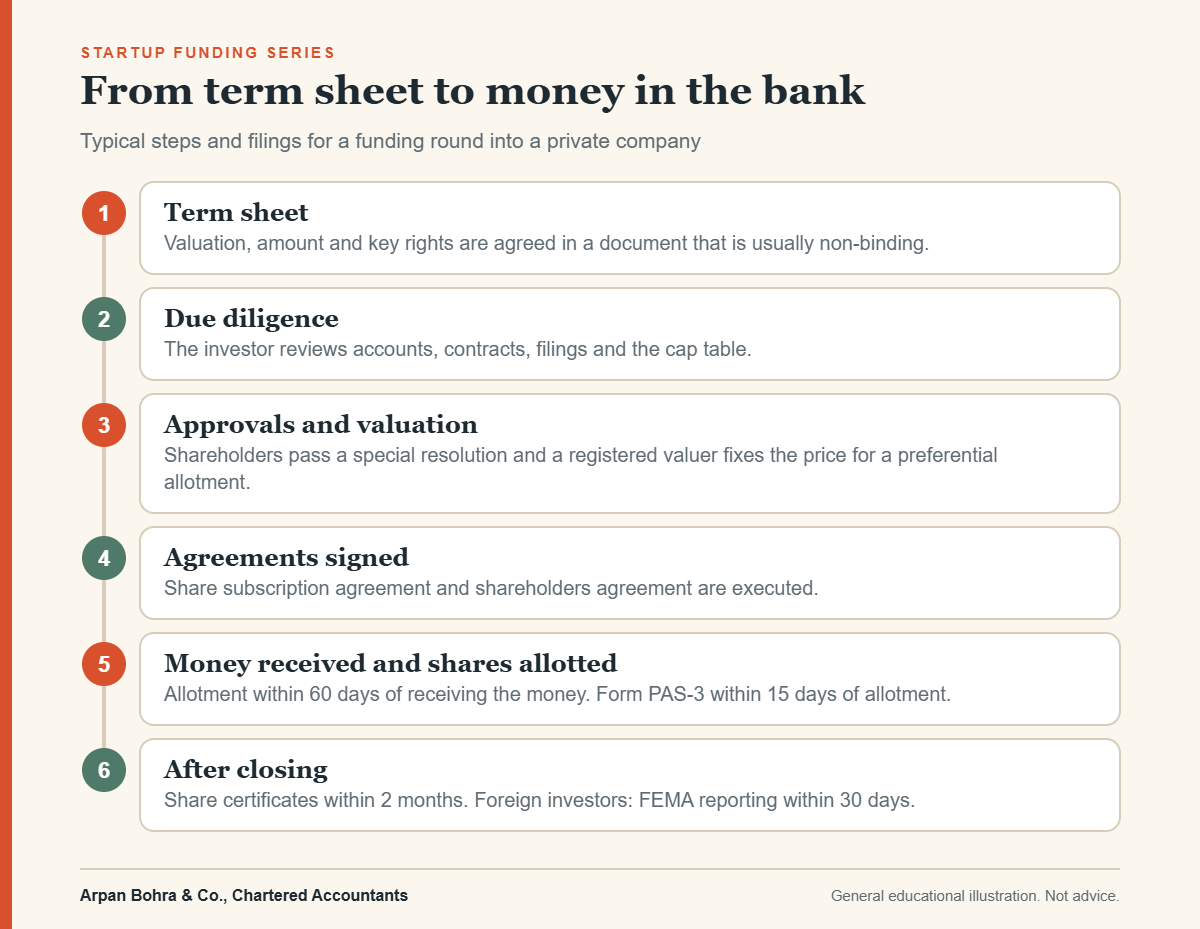
The same company-law steps apply whichever investor you choose. Allotment to a new investor is normally a preferential allotment under Section 62(1)(c) through the private placement process. Our guide on how to issue shares in a private limited company covers each form, and the article on startup valuation methods explains how the price is reached.
If the investor is outside India, read our note on FEMA reporting for foreign investment. Investor rights are usually recorded in a shareholders agreement, and the investor will run a due diligence review before closing.
Common mistakes to avoid
Treating a term sheet as the end of the deal. It is usually non-binding on price and rights, and the definitive agreements can change terms. Read the shareholders agreement line by line before signing.
- Giving equity informally. A promise of shares in a chat message is not an allotment. Shares are issued only by following the Companies Act process.
- Ignoring dilution. Every new round reduces existing percentages. Model it before agreeing the price.
- Skipping checks on the investor. Ask for identity, source of funds and track record, as the investor will ask the same of you.
- Using the money before filing. A company cannot use private placement money until the return of allotment in Form PAS-3 is filed.
Frequently asked questions
Is angel tax still payable?
Can an angel fund invest in any startup?
How much equity does an investor take?
Can a startup raise from both angels and VCs?
Is a term sheet legally binding?
Do foreign investors follow different rules?
Arpan Bohra & Co., Chartered Accountants, Himayat Nagar, Hyderabad.
This article is shared for general professional education. Readers may write to the firm for information about its practice areas.
General educational information as at 21 November 2026. It is not legal, tax or investment advice and does not create a professional relationship. Examples use assumed figures for illustration only. Provisions, rates and thresholds change; verify the current law and notifications before acting.
This article is for general information and is not professional advice. Law and rates change; please consult us before you act.