An IT-services company in HITEC City invoices a Singapore client in rupees; the client pays from an SNRR account. A stock broker receives brokerage in INR from an FPI’s repatriable account. A reinsurance broker never sees a separate remittance because its commission is retained from the net premium. Does each of these satisfy the condition “payment received in convertible foreign exchange” for an export of services? Circular No. 263/09/2026-GST, dated 26 October 2026, deals with these and with the realisation period for goods under rule 96B.
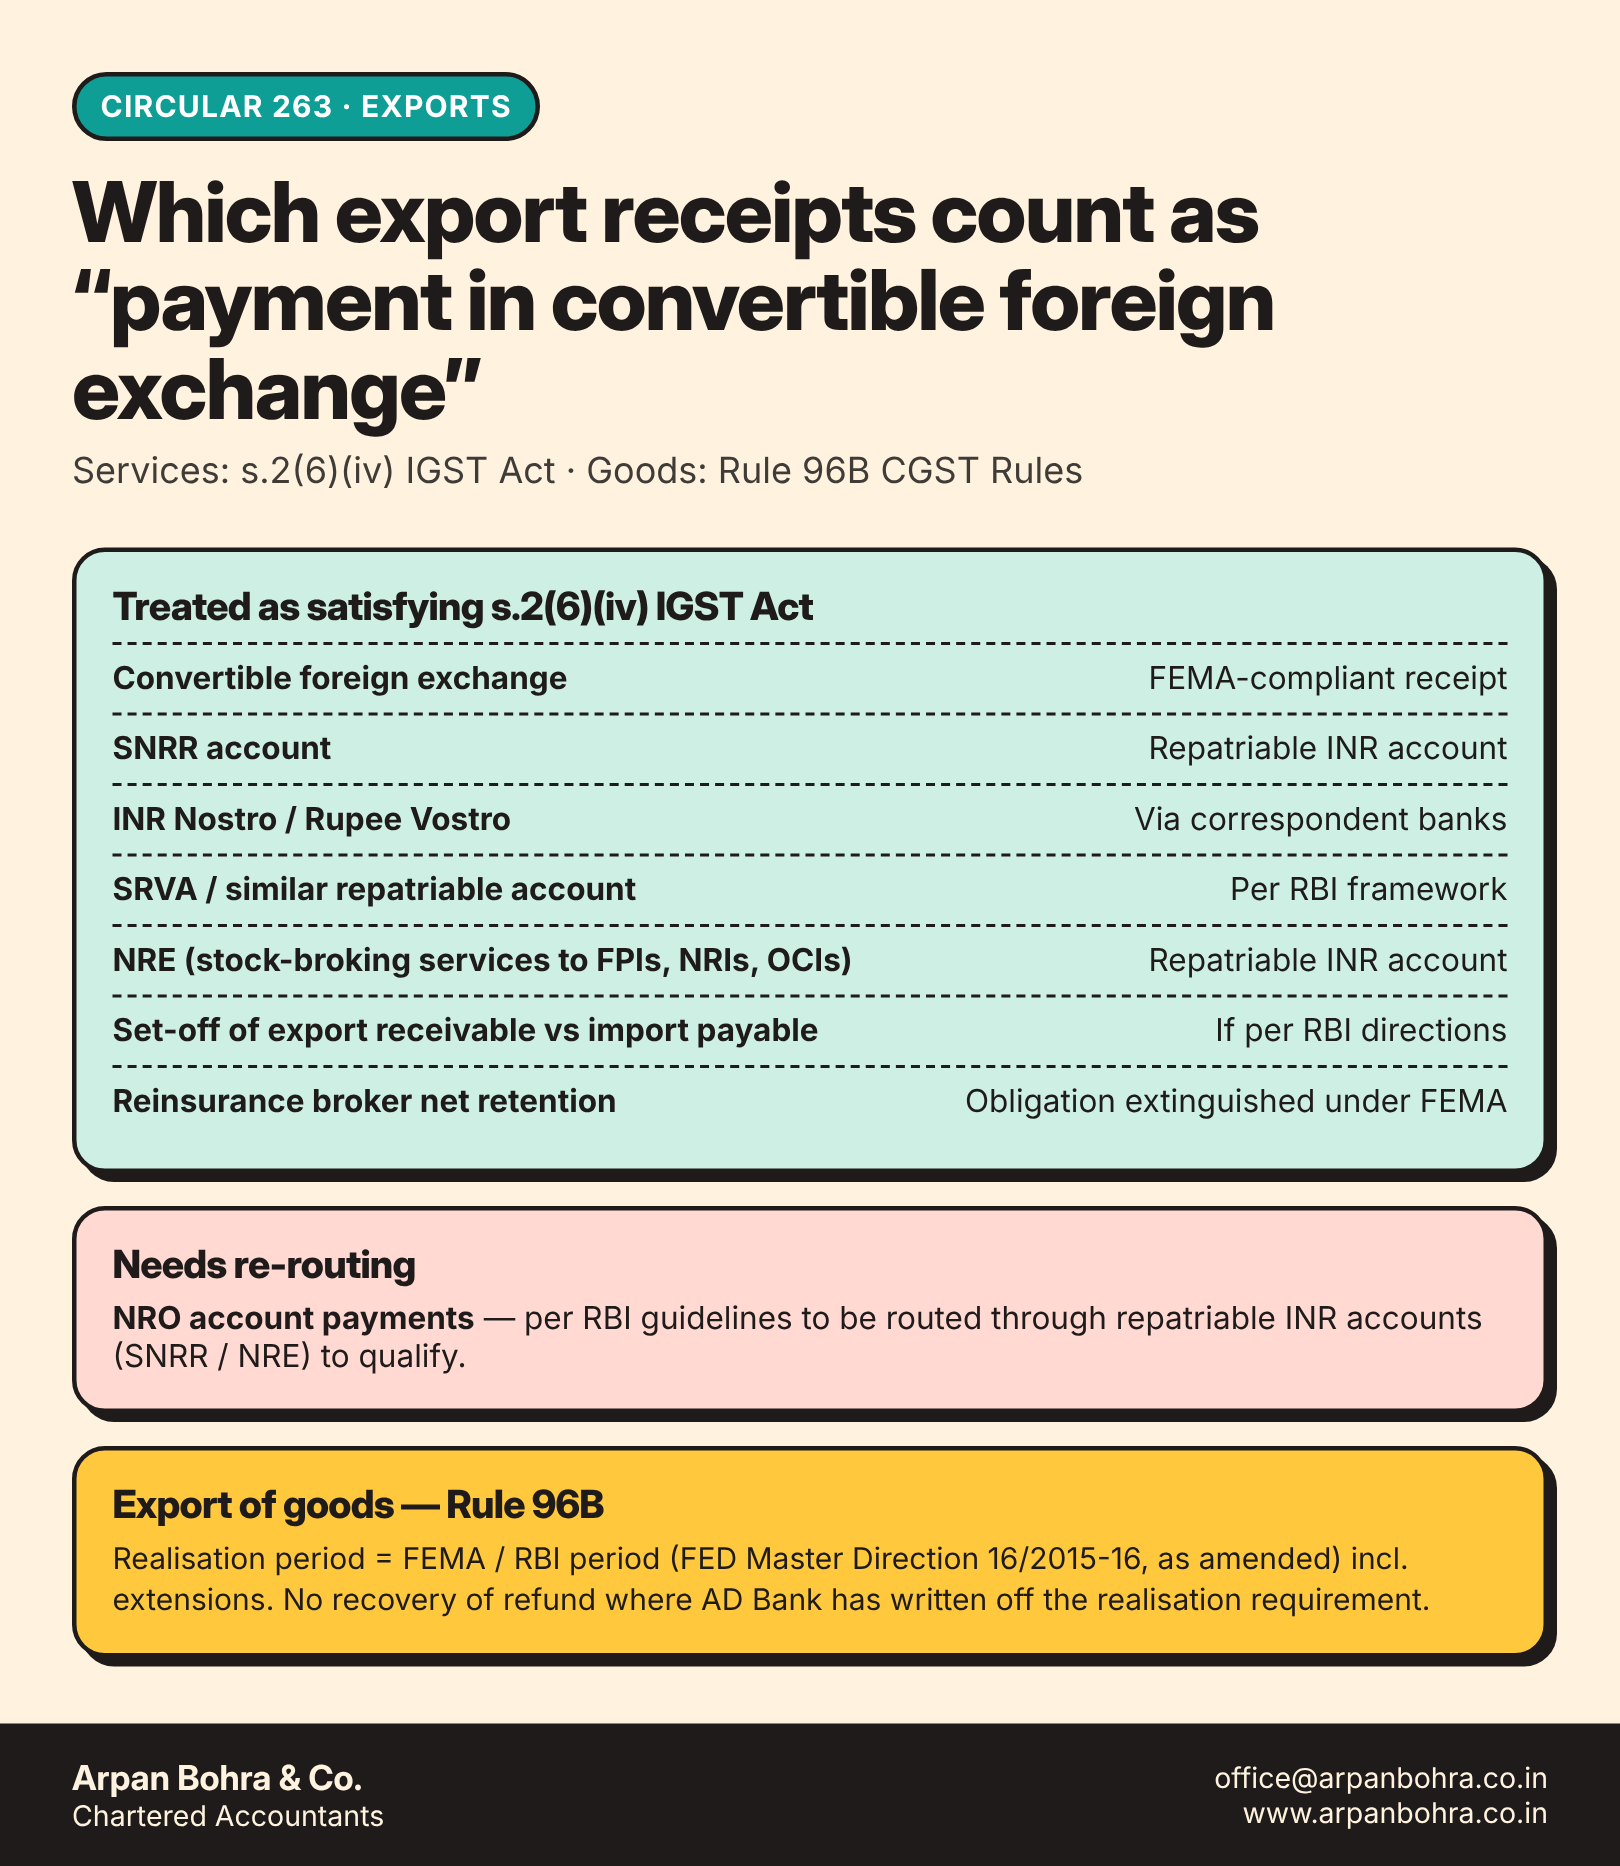
In short: receipts in convertible foreign exchange or repatriable INR accounts (SNRR, INR Nostro / Rupee Vostro, SRVA or similar), properly permitted set-offs, and net retention by reinsurance brokers are treated as fulfilling section 2(6)(iv) of the IGST Act, 2017; for goods, the realisation period under rule 96B is whatever FEMA / RBI prescribes, including extensions.
Export of services: the condition
Section 2(6) of the IGST Act defines “export of services”. Sub-clause (iv) requires that the supplier has received payment in convertible foreign exchange or, where permitted by RBI, in Indian rupees. The Circular reads this together with the Foreign Exchange Management (Manner of Receipt and Payment) Regulations, 2023 (FEMA 14R/2023), under which export receipts for countries other than Nepal, Bhutan and Asian Clearing Union members may be in INR or any foreign currency, routed through INR Nostro (Rupee Vostro) accounts of correspondent banks or repatriable INR accounts such as SRVA and SNRR.
It builds on Circular No. 202/14/2023-GST dated 27.10.2023, which accepted receipts from Special Rupee Vostro Accounts, subject to the Foreign Trade Policy, 2023 and RBI circulars.
What the Circular clarifies
| Situation | Position in the Circular |
|---|---|
| Payment in convertible foreign exchange | Satisfies sub-clause (iv) |
| Payment in repatriable INR accounts: SNRR, INR Nostro, other similar accounts | Satisfies sub-clause (iv) |
| Stock-broker services to overseas FPIs, NRIs and OCIs, paid through repatriable INR accounts (SNRR, NRE) | May be considered to satisfy sub-clause (iv) |
| Payment through NRO accounts | Should, per RBI guidelines, be routed through repatriable INR accounts (SNRR, NRE) to be considered as satisfying sub-clause (iv) |
| Set-off of export receivables against import payables | Satisfies sub-clause (iv) if the set-off is in accordance with RBI directions. Under extant guidelines set-off is allowed for goods against goods and services against services with conditions; the Circular notes that from 1 October 2026, with the Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026, those conditions are not applicable to such transactions |
| Reinsurance broker commission settled by net retention | Treated as satisfying sub-clause (iv), because under FEMA the obligation to realise and repatriate is extinguished through the net retention mechanism |
Export of goods: Rule 96B
Rule 96B requires a refund amount paid on exports to be deposited back, with interest, within thirty days from the expiry of the FEMA period (or extended period), to the extent sale proceeds are not realised. No recovery is to be effected where the realisation requirement has been written off, wholly or partly, by the RBI on merits.
The Circular clarifies that the time limit and the amount to be realised are governed by FEMA, 1999, as framed by the RBI. The relevant period under the IGST Act is therefore that prescribed in FED Master Direction No. 16/2015-16 dated 01.01.2016 (last amended on 05.06.2026, as stated in the Circular) and amended from time to time, including any extension. Where the requirement has been written off, wholly or partly, by the AD Bank, recovery under rule 96B shall not be done.
Where views can differ
- Written off “by RBI on merits” versus “by the AD Bank”. Rule 96B speaks of write-off by the Reserve Bank of India on merits; para 3.1 of the Circular says recovery shall not be done where the requirement is written off by the AD Bank. The two phrases are not identical. A taxpayer relying on an AD Bank write-off may cite the Circular; the department may point to the rule text. The Circular’s wording favours the taxpayer (confirm in practice at the time of reply).
- Date of the 2026 Regulations. The Circular refers to FEMA regulations effective 1 October 2026 for set-off conditions. Exporters with transactions straddling that date should review which framework governed each receipt.
- Past periods. The Circular does not state whether it applies retrospectively; refund claims already rejected on these grounds may be tested on appeal (litigative).
Documentation worth holding
For each export of services where payment is in INR: the FIRC or bank advice showing the account type (SNRR / Nostro / NRE); for set-off, the AD Bank-compliant settlement record; and for brokers, the engagement terms showing the client category. For goods, the shipping bill, the realisation tracking and any AD Bank extension or write-off letter.
Risk view
| Issue | Risk |
|---|---|
| NRO account receipts not routed via repatriable account | High — payment condition may not be met |
| Set-off not in accordance with RBI directions | High |
| Rule 96B recovery despite AD Bank write-off | Low after the Circular |
| Realisation beyond the FEMA period without extension | High |
Frequently asked questions
Is INR payment from abroad acceptable for export of services? Under the Circular, yes when received through the repatriable accounts listed and as FEMA permits.
What about a reinsurance broker whose commission is netted off? It is treated as having satisfied the condition.
Who prescribes the period for realisation of export proceeds of goods? The RBI under FEMA; the Circular points to FED Master Direction No. 16/2015-16, as amended.
Can a refund be recovered after a write-off? The Circular says no recovery under rule 96B where the realisation requirement has been written off, wholly or partly; the procedure to establish the write-off is not described in it.
Sources
- CBIC Circular No. 263/09/2026-GST dated 26.10.2026 and Circular No. 202/14/2023-GST dated 27.10.2023 — CBIC website.
- Section 2(6), IGST Act, 2017; Rule 96B, CGST Rules, 2017; RBI website for FEMA regulations and Master Directions referred to.
Read the other circulars of 26 October 2026
- 8 GST Circulars in One Day: Circulars 257 to 264 of 2026 Decoded
- GST Registration in 2026: What Circular 257 Means for Your Documents, Premises Proof and REG-03
- From Show Cause Notice to First Appeal: What Circular 258 Expects of GST Officers
- GST Appeal Pre-deposit Decoded: Admitted Amount, 10% Deposit and Refund under Circular 259
- Input Service Distributor: Seven Answers from Circular 260 Every Multi-Location Business Should Read
- Banks and NBFCs: Claiming ITC under Section 17(4) and Reporting It Right in GSTR-3B (Circular 261)
- Demo Cars and ITC: Circular 262 Lifts the Block for Dealer-Agency Model Dealers
- Rule 96(10) Is Gone, and Retrospectively: What Circular 264 Means for Exporters
Arpan Bohra & Co., Chartered Accountants
Himayat Nagar, Hyderabad
Email: office@arpanbohra.co.in | GST queries: gst@arpanbohra.co.in / 9010558981
Website: www.arpanbohra.co.in | LinkedIn
Disclaimer. This article is a general educational discussion of the Circular and the provisions referred to. It is not legal advice or an opinion on any particular facts, creates no professional engagement, and is not a solicitation of work. Circulars, rules and judgments change and may be read differently by different forums; the original text of each document should be read before reliance, and professional advice taken on specific facts. Judgments are cited as they appear in the Circular unless a separate source is stated. Items marked (confirm) require verification against the current text of the law.
This article is for general information and is not professional advice. Law and rates change; please consult us before you act.