On 26 October 2026 the CBIC issued eight GST circulars in a single day, Nos. 257 to 264. Taken together, they touch the whole life of a GST taxpayer: how to get registered, how a demand should be raised and decided, what to deposit to appeal, how credit moves through an Input Service Distributor, how banks and NBFCs report ITC, whether demo cars carry ITC, which export receipts count, and what happens to rule 96(10).
In short: three circulars are about process fairness (257, 258, 259), three are about input tax credit (260, 261, 262), and two are about exports and refunds (263, 264). Two of them, 262 and 264, reverse or retreat from earlier departmental positions.
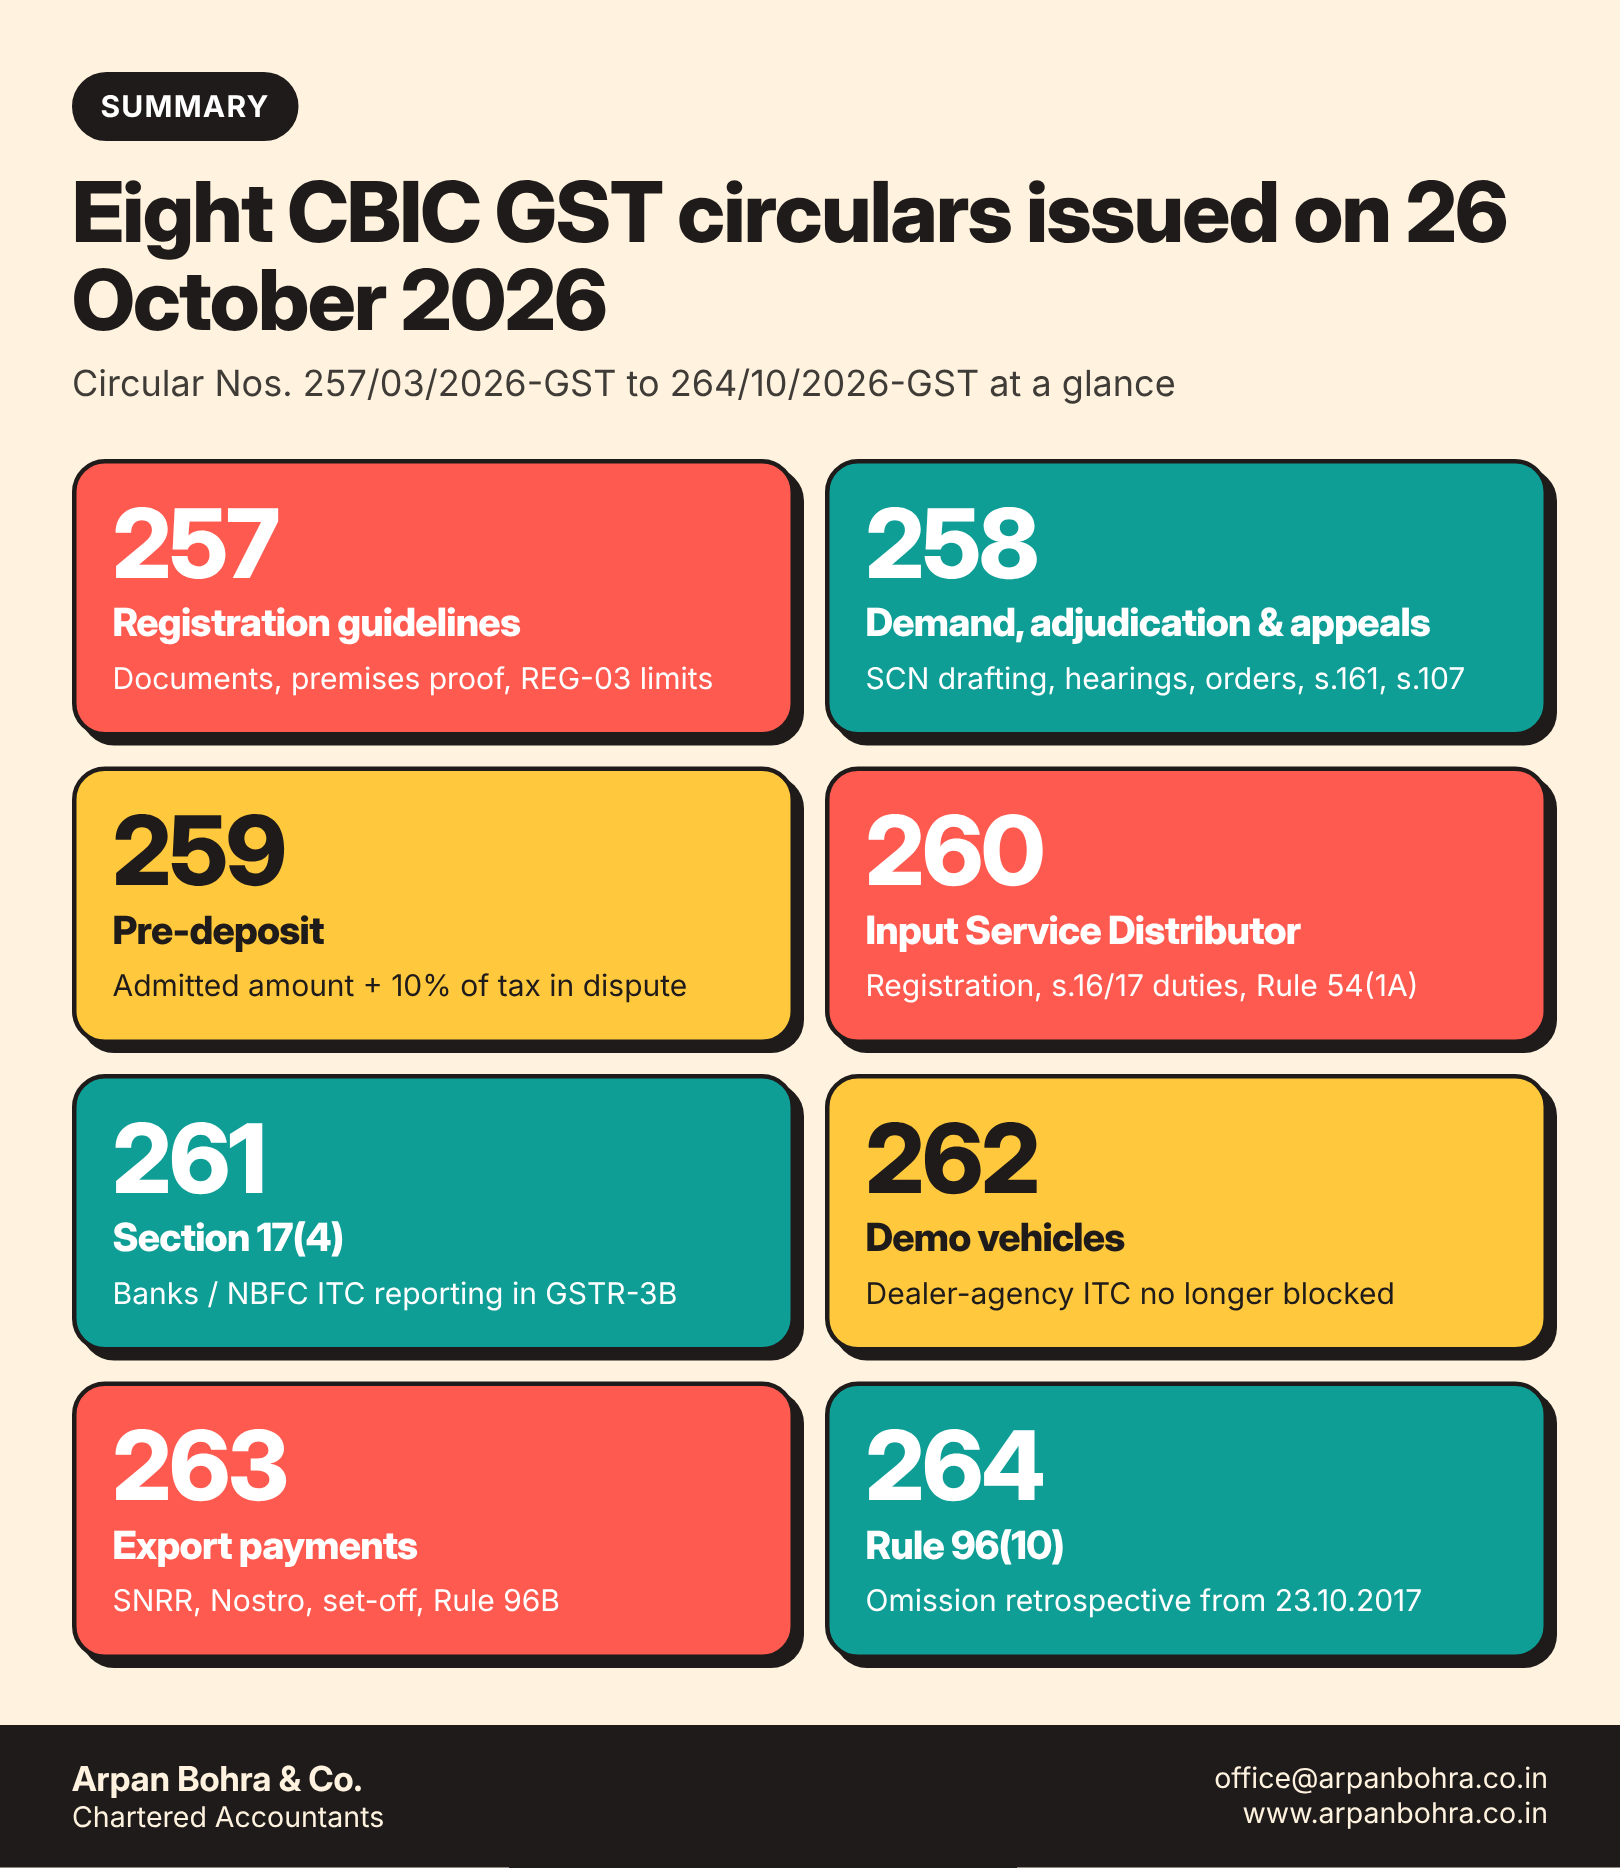
At a glance
| Circular No. | Subject | Key points | Detailed article |
|---|---|---|---|
| 257/03/2026-GST | GST registration guidelines | Applicant-side guide to REG-01: legal-name match, photographs, up to 10 authorised signatories, premises proof by category (own, rented, consent, co-working, SEZ), REG-03 only for three deficiencies, 3 / 7 / 30-day clocks, Rule 14A simplified registration. | For details, refer to the article: GST registration guidelines |
| 258/04/2026-GST | Demand, adjudication and appeals | Content of a show cause notice, extended-period allegations (G.R. Infra), personal hearings (max four), speaking orders, section 75(7), section 161 rectification, first appeal scrutiny, limitation, additional evidence. | For details, refer to the article: Demand, adjudication and appeals |
| 259/05/2026-GST | Pre-deposit for appeals | Admitted amount paid in full; 10% of tax in dispute as pre-deposit; Tribunal stage computed on the liability confirmed by the Appellate Authority; refund through RFD-01 (S. No. 7); interest by payment date; remand. | For details, refer to the article: Pre-deposit for appeals |
| 260/06/2026-GST | Input Service Distributor | More than one ISD registration allowed; recipient complies with sections 16/17 and reverses; distribution in the month ISD ascertains prima facie eligibility; rule 54(1A) is only a transfer mechanism. | For details, refer to the article: Input Service Distributor |
| 261/07/2026-GST | Section 17(4): banks and NBFCs | Who can opt; all qualifying registrations must follow; second-proviso scope; GSTR-3B sequence (Tables 4(B)(1), 4(B)(2), 4(A)(5), 4(D)(1)); IMS; no adverse view on past reporting method. | For details, refer to the article: Section 17(4): banks and NBFCs |
| 262/08/2026-GST | ITC on demo vehicles | Para 4.6 of Circular 231/25/2024-GST withdrawn; ITC on demo vehicles not blocked under section 17(5)(a) for dealer-agency model. | For details, refer to the article: ITC on demo vehicles |
| 263/09/2026-GST | Export payment realisation | SNRR, Nostro, repatriable INR, NRE for brokers, set-off, reinsurance net retention treated as meeting section 2(6)(iv) IGST Act; NRO to be routed; Rule 96B period per FEMA / RBI. | For details, refer to the article: Export payment realisation |
| 264/10/2026-GST | Rule 96(10) omission | Omission effective retrospectively from 23.10.2017 after Goodluck India (SC, 06.08.2026); pending proceedings to follow; same for rules 89(4A), 89(4B). | For details, refer to the article: Rule 96(10) omission |
Common threads
1. The Board is writing down what the courts have said. Circular 258 draws on the Supreme Court in G.R. Infra Project Ltd, the Telangana and Andhra Pradesh High Courts, Armour Security and Saheli Leasing. Circular 264 follows Goodluck India Limited (06.08.2026). Circular 263 aligns GST with FEMA. Circular 262 withdraws a para after noting its discriminatory effect.
2. Procedural fairness is the theme of the first three. The registration Circular limits the queries an officer may raise; the adjudication Circular asks for notices that carry their own particulars and orders that discuss every submission; the pre-deposit Circular removes inconsistent practice on computing and refunding the deposit.
3. Credit mechanics are being tightened and clarified at the same time. The ISD Circular places eligibility on the recipient; the section 17(4) Circular prescribes the GSTR-3B sequence; the demo-vehicle Circular narrows a block.
What changes, and what does not
| Area | Change | Still open |
|---|---|---|
| Registration | Document-by-premises checklist and officer query limits | Treatment of State-specific fields; officer-level compliance on the ground |
| SCN and orders | Detailed drafting standards; para 17 says officers must not cite the Circular | Whether taxpayers can rely on it directly |
| Pre-deposit | Admitted vs disputed amount; Tribunal computed on confirmed liability; refund route | Rate and cap in sections 107(6), 112(8) to be read from the Act as amended |
| ISD | Multiple ISDs; recipient compliance; same-month rule explained | Effect on past refund computations (rule 54(1A)) |
| Section 17(4) | Opt-in is entity-wide for qualifying registrations | Reconciliation of past inconsistent choices |
| Demo vehicles | Dealer-agency model no longer blocked | Past periods and time limits for re-claim |
| Exports | Repatriable INR routes accepted; Rule 96B period per RBI | Retrospectivity not stated |
| Rule 96(10) | Retrospective from 23.10.2017 for pending proceedings | Closed matters and limitation |
Risk view across the eight circulars
| Circular | Where exposure sits | Level |
|---|---|---|
| 257 | Premises-proof mismatch; missing REG-03 reply | High |
| 258 | Notices or orders that depart from para 5, 10, 11, 13 | High for the department; appeals benefit |
| 259 | Wrong admitted / disputed split; incorrect Tribunal deposit | Moderate to High |
| 260 | Distribution not attributable; reversals left with wrong entity | High |
| 261 | Inconsistent opt-in; wrong table in GSTR-3B | High |
| 262 | Past denials not revisited | Moderate |
| 263 | NRO receipts; non-compliant set-off | High |
| 264 | Closed refund matters | Uncertain |
How to use this summary
This is a summary for orientation. Each circular has an article of its own with the provisions, a table of clarifications, views that can be taken on contested points, and a risk view. Please download the individual article from the link in the table above, and refer to the circular text on the CBIC website before relying on any proposition.
Frequently asked questions
Are all eight circulars issued under the same power? Each states that it is issued under section 168(1) of the CGST Act, 2017.
Which circular affects pending litigation the most? Circulars 258, 259 and 264 bear directly on pending notices, appeals and refund proceedings.
Does any circular create new statutory rights? The Circulars are clarifications and guidelines under section 168(1); statutory rights arise from the Act and rules.
Are any earlier circulars withdrawn? Circular 262 withdraws para 4.6 of Circular No. 231/25/2024-GST dated 10.09.2024.
Where can the circular text be found? On the CBIC website, with each article linking to the specific circular.
Sources
- CBIC Circular Nos. 257/03/2026-GST to 264/10/2026-GST dated 26.10.2026 — CBIC website.
- Individual articles linked in the table above.
Read the other circulars of 26 October 2026
- GST Registration in 2026: What Circular 257 Means for Your Documents, Premises Proof and REG-03
- From Show Cause Notice to First Appeal: What Circular 258 Expects of GST Officers
- GST Appeal Pre-deposit Decoded: Admitted Amount, 10% Deposit and Refund under Circular 259
- Input Service Distributor: Seven Answers from Circular 260 Every Multi-Location Business Should Read
- Banks and NBFCs: Claiming ITC under Section 17(4) and Reporting It Right in GSTR-3B (Circular 261)
- Demo Cars and ITC: Circular 262 Lifts the Block for Dealer-Agency Model Dealers
- Export Payments and GST: SNRR, Nostro, Set-off and Rule 96B under Circular 263
- Rule 96(10) Is Gone, and Retrospectively: What Circular 264 Means for Exporters
Arpan Bohra & Co., Chartered Accountants
Himayat Nagar, Hyderabad
Email: office@arpanbohra.co.in | GST queries: gst@arpanbohra.co.in / 9010558981
Website: www.arpanbohra.co.in | LinkedIn
Disclaimer. This article is a general educational discussion of the Circular and the provisions referred to. It is not legal advice or an opinion on any particular facts, creates no professional engagement, and is not a solicitation of work. Circulars, rules and judgments change and may be read differently by different forums; the original text of each document should be read before reliance, and professional advice taken on specific facts. Judgments are cited as they appear in the Circular unless a separate source is stated. Items marked (confirm) require verification against the current text of the law.
This article is for general information and is not professional advice. Law and rates change; please consult us before you act.